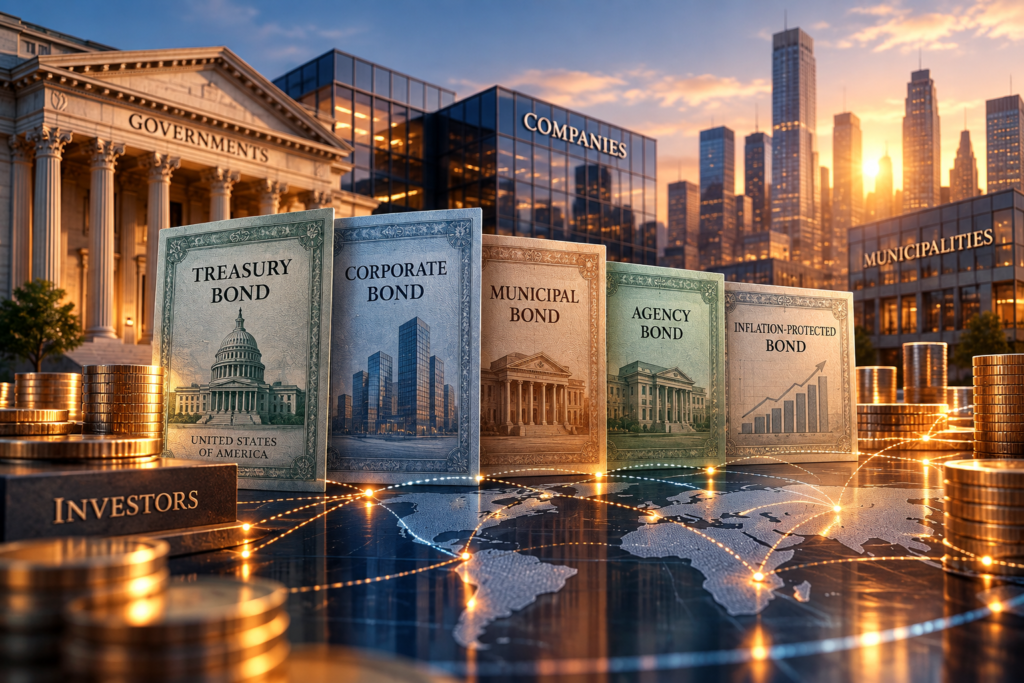
The bond market is the part of the financial system where governments, companies, municipalities, and other organizations borrow money by issuing debt securities. Investors buy those bonds in exchange for interest payments and the expected return of principal at maturity. Unlike stocks, bonds generally represent lending rather than ownership.
The bond market plays a central role in modern finance because it allows governments and businesses to raise large amounts of capital over different time periods. It also gives investors access to assets with different combinations of income, maturity, credit quality, and interest-rate sensitivity.
What Is a Bond?
A bond is a debt security issued by an organization that wants to borrow money. When an investor buys a bond, the investor is effectively lending money to the issuer under predefined terms.
Those terms usually include:
- face value;
- coupon rate;
- maturity date;
- payment schedule;
- repayment conditions.
Suppose a company issues a bond with a face value of $1,000, a 5% annual coupon, and a ten-year maturity. An investor who owns the bond may receive $50 of interest each year and, assuming the issuer meets its obligations, $1,000 when the bond matures.
What Is the Bond Market?
The bond market is the collection of markets where debt securities are issued and traded. It includes securities from governments, corporations, municipalities, financial institutions, and other borrowers.
Unlike the stock market, much of bond trading takes place over the counter rather than through one centralized exchange. Dealers, banks, brokers, asset managers, pension funds, insurance companies, and institutional investors all participate in the market.
The bond market is often divided into two broad areas:
- primary market;
- secondary market.
Primary Bond Market
The primary bond market is where new debt securities are issued for the first time. The issuer receives capital from investors.
A corporation might issue bonds to finance:
- expansion;
- acquisitions;
- equipment;
- refinancing;
- working capital.
Governments can issue bonds to finance public spending, infrastructure, or budget needs. The ability to raise debt is an important part of corporate finance because management must decide how much borrowing is appropriate and how debt fits with other sources of capital.
Secondary Bond Market
After a bond has been issued, investors can trade it with other market participants in the secondary market. The original issuer usually does not receive money from these later transactions.
Secondary trading provides liquidity. An investor who owns a ten-year bond does not necessarily need to hold it for the full ten years if another buyer is available.
The bond’s market price can change considerably before maturity.
How Do Bonds Work?
A basic bond transaction involves two sides:
Issuer: borrows money.
Investor: provides capital.
In return, the issuer promises payments according to the bond’s terms. These payments often include periodic interest plus repayment of principal at maturity.
The value of a bond depends on more than the coupon rate. Investors also consider:
- market interest rates;
- credit quality;
- remaining maturity;
- liquidity;
- inflation expectations.
This is why a bond can trade above or below its original face value.
Face Value
Face value, sometimes called par value, is the amount the issuer promises to repay at maturity under normal conditions.
A common face value might be:
$1,000
If the bond trades for $950, it is trading below par.
If it trades for $1,050, it is trading above par.
The market price can fluctuate even though the face value remains unchanged.
Coupon Rate
The coupon rate determines the bond’s stated interest payment.
Suppose a bond has:
Face value: $1,000
Coupon rate: 6%
Annual coupon payment:
$60
If interest is paid twice per year, the investor might receive:
$30 every six months
The coupon itself does not necessarily change simply because market interest rates move.
Maturity
Maturity is the date when the issuer is expected to repay the bond’s principal.
Bonds can have very different maturities:
- short-term;
- medium-term;
- long-term.
Longer maturities usually create greater exposure to changes in interest rates because investors are committing capital for a longer period.
Bond Prices and Interest Rates
Bond prices and market interest rates generally move in opposite directions.
Suppose an investor owns a bond paying:
4%
New bonds of similar credit quality are later issued at:
6%
The older 4% bond becomes less attractive. Its market price may fall so that its effective return becomes more competitive with newer bonds.
The reverse can also occur. If new bonds offer only 3%, an older bond paying 4% may become more valuable.
This relationship is one of the most important concepts in fixed-income investing.
Why Bond Prices Fall When Rates Rise
Imagine two bonds with similar risk.
Bond A pays:
$40 per year
Bond B, newly issued, pays:
$60 per year
If both cost $1,000, investors would generally prefer Bond B.
For Bond A to become competitive, its market price may need to decline.
This adjustment happens through secondary-market pricing.
Yield
Yield describes the return generated by a bond relative to its price.
Several yield measures can be used.
Current Yield
A simplified current-yield formula is:
Annual Coupon ÷ Market Price
Suppose a bond pays:
$50 per year
and trades at:
$900
Current yield:
5.56%
This measure is useful but incomplete because it does not account for the bond eventually moving toward its face value at maturity.
Yield to Maturity
Yield to maturity, or YTM, estimates the annualized return an investor could earn if the bond is held until maturity, assuming scheduled payments are made and certain assumptions are met.
YTM reflects:
- coupon payments;
- market price;
- face value;
- time remaining.
It is a more complete measure than current yield, although actual investor returns can still differ.
Yield to Call
Some bonds can be redeemed before their stated maturity date.
For these securities, investors may also consider yield to call.
A callable bond can be disadvantageous to the investor if the issuer redeems it when interest rates fall. The investor receives the principal back but may have to reinvest at lower rates.
Main Types of Bonds
The bond market contains several major categories.
Government Bonds
National governments issue debt to finance public spending and manage government borrowing.
These securities may be considered relatively low credit risk when issued by financially strong governments in their own currencies, but they are not free of risk.
Government bonds can still face:
- inflation risk;
- interest-rate risk;
- currency risk;
- sovereign risk.
The level of risk differs substantially between countries.
Treasury Securities
In the United States, Treasury securities include instruments with different maturities.
They are commonly divided into:
- Treasury bills;
- Treasury notes;
- Treasury bonds.
Treasuries are widely used as reference securities in global financial markets and play an important role in setting benchmark interest rates.
Corporate Bonds
Companies issue corporate bonds to borrow capital from investors.
The funds can be used for:
- acquisitions;
- expansion;
- capital investment;
- refinancing.
Corporate bonds generally offer higher yields than high-quality government debt because investors face additional credit risk.
If the issuing company encounters serious financial problems, bondholders may not receive all promised payments.
Municipal Bonds
Municipal bonds are issued by states, cities, local authorities, and other public entities.
They can finance:
- roads;
- schools;
- hospitals;
- utilities;
- infrastructure.
Their tax treatment can differ by jurisdiction, so investors need to understand the specific rules applicable to the security.
Agency Bonds
Agency bonds are issued by government-related organizations or institutions.
The risk of these securities depends on the issuer and whether there is any explicit or implicit government support.
Investors should not assume every agency bond has the same level of protection.
Investment-Grade Bonds
Investment-grade bonds are issued by borrowers considered to have relatively strong credit quality.
Credit-rating agencies generally assign these securities higher ratings.
Investment-grade bonds typically offer lower yields than lower-quality debt because investors perceive a lower probability of default.
High-Yield Bonds
High-yield bonds have lower credit ratings and therefore usually offer higher yields.
They are also sometimes called:
- speculative-grade bonds;
- junk bonds.
Higher yields compensate investors for greater risk, including a higher probability of default or financial distress.
High yield does not mean high return is guaranteed.
Secured vs Unsecured Bonds
A secured bond is backed by specific assets or collateral.
An unsecured bond depends more heavily on the issuer’s general creditworthiness.
In bankruptcy or restructuring, secured creditors may have stronger claims on certain assets.
However, recovery still depends on:
- asset value;
- legal structure;
- other creditors.
Convertible Bonds
Convertible bonds allow investors to convert debt into shares under specified conditions.
They combine characteristics of:
- bonds;
- equity.
Investors may accept a lower coupon because the conversion feature provides potential upside if the company’s stock price rises substantially.
Zero-Coupon Bonds
Zero-coupon bonds do not make regular interest payments.
Instead, they are generally issued at a discount to face value.
For example, an investor might pay:
$700
for a bond that matures at:
$1,000
The difference contributes to the investor’s return.
Because much of the value is received at maturity, zero-coupon bonds can be particularly sensitive to interest-rate changes.
Floating-Rate Bonds
Floating-rate bonds have coupons that adjust periodically according to a reference interest rate.
This can reduce some interest-rate sensitivity compared with fixed-rate bonds.
However, these securities can still carry:
- credit risk;
- liquidity risk;
- spread risk.
Fixed-Rate Bonds
Fixed-rate bonds pay a coupon that remains unchanged under normal conditions.
They provide predictable nominal income.
Their market price can still fluctuate significantly when prevailing interest rates change.
The Bond Yield Curve
A yield curve shows interest rates across bonds with different maturities, often using government securities as a benchmark.
A typical curve compares yields on:
- short-term debt;
- medium-term debt;
- long-term debt.
Its shape provides information about market expectations and financial conditions.
Normal Yield Curve
A normal yield curve slopes upward.
Longer-term bonds offer higher yields than shorter-term bonds.
This may reflect compensation for:
- inflation uncertainty;
- interest-rate risk;
- longer capital commitment.
Flat Yield Curve
A flat curve occurs when short- and long-term yields are relatively similar.
This can indicate uncertainty about future economic and monetary conditions.
Inverted Yield Curve
An inverted yield curve occurs when short-term yields are higher than long-term yields.
This structure can appear when investors expect:
- slower economic growth;
- future interest-rate reductions.
An inverted curve has often received attention as an economic signal, but it should not be treated as a guaranteed prediction of future conditions.
Bond Market vs Stock Market
Stocks and bonds represent different claims.
| Bonds | Stocks |
|---|---|
| Debt ownership | Equity ownership |
| Usually defined interest payments | Dividends are not guaranteed |
| Principal generally due at maturity | No maturity date for common stock |
| Bondholders have creditor claims | Shareholders own part of the company |
| Typically lower priority risk than equity | Higher risk in liquidation |
Bonds can provide more predictable contractual payments, while stocks offer greater participation in business growth.
Investors often use both asset classes within diversified portfolios.
Bond Indices
Just as stock market indices track groups of equities, bond indices measure the performance of defined groups of fixed-income securities.
A bond index can represent:
- government bonds;
- corporate debt;
- investment-grade bonds;
- high-yield debt;
- specific maturity ranges.
Bond indices are commonly used as benchmarks for fixed-income portfolios and bond funds.
Because bond markets contain thousands of individual securities, indices provide a practical way to measure broad market performance.
Bond Funds
Investors can gain bond exposure through funds rather than purchasing individual securities.
Common vehicles include:
- mutual funds;
- ETFs.
Bond funds can provide diversification across many issuers and maturities.
However, a bond fund does not function exactly like holding one individual bond to maturity. The fund continuously owns and trades securities, so it does not have one single maturity date at which the investor automatically receives face value.
Bond ETFs
Bond ETFs trade on stock exchanges and can provide access to specific bond-market segments.
Examples include funds focused on:
- government debt;
- corporate bonds;
- high-yield bonds;
- short-term securities.
Their prices can fluctuate throughout the trading day.
ETF liquidity and the liquidity of the underlying bonds are related but not identical.
Major Risks in Bonds
Bonds are often considered less volatile than stocks, but they are not risk-free.
Interest-Rate Risk
Interest-rate risk is the possibility that bond prices fall when market rates rise.
This risk is usually greater for:
- longer maturities;
- lower coupons.
Two bonds with the same credit quality can therefore react differently to the same interest-rate change.
Credit Risk
Credit risk is the possibility that the issuer cannot meet its obligations.
Potential outcomes include:
- missed interest payments;
- restructuring;
- default;
- partial recovery.
Corporate and lower-rated bonds generally carry more credit risk than high-quality government debt.
Default Risk
Default occurs when an issuer fails to meet required debt obligations.
The investor may recover some money through:
- restructuring;
- asset sales;
- bankruptcy proceedings.
Recovery can be far below the bond’s face value.
Inflation Risk
Inflation reduces the purchasing power of fixed payments.
Suppose a bond pays:
3%
while inflation is:
5%
The investor may receive positive nominal income while losing purchasing power in real terms.
This is particularly important for long-term fixed-rate bonds.
Liquidity Risk
Some bonds trade frequently.
Others may trade rarely.
Low liquidity can create:
- wider bid-ask spreads;
- less predictable execution prices;
- difficulty selling large positions.
The bond’s quoted value may therefore differ from the price at which an investor can actually trade.
Reinvestment Risk
Reinvestment risk occurs when interest payments or returned principal must be reinvested at lower rates.
This can happen when:
- market rates decline;
- a callable bond is redeemed early.
Investors may receive their money back sooner than expected but struggle to find a comparable yield.
Call Risk
Callable bonds give the issuer the right to repay debt early under certain conditions.
Issuers may exercise this option when rates fall.
The investor loses the higher-yielding bond and must potentially reinvest at a lower rate.
Currency Risk
Investors buying bonds denominated in foreign currencies face exchange-rate risk.
Even if the bond performs well in its local currency, adverse currency movements can reduce the investor’s return when converted back into the home currency.
Duration
Duration is a measure used to estimate how sensitive a bond’s price is to changes in interest rates.
A higher duration generally means greater price sensitivity.
For example, a bond portfolio with a duration of approximately:
7 years
may decline roughly 7% if interest rates rise by 1 percentage point, all else equal.
This is only an approximation, but it provides a practical way to compare interest-rate exposure.
Duration vs Maturity
Maturity tells investors when principal is scheduled to be repaid.
Duration measures interest-rate sensitivity.
The two are related but not identical.
A long-maturity bond can have a different duration from another bond with the same maturity because of:
- coupon rate;
- cash-flow timing.
Credit Ratings
Credit-rating agencies assess the ability of issuers to meet debt obligations.
Ratings can help investors compare credit quality.
However, ratings are opinions rather than guarantees.
Credit conditions can deteriorate between rating reviews, and investors should not rely on a rating as the only measure of risk.
What Moves the Bond Market?
Bond prices and yields respond to several major forces.
Central Bank Policy
Changes in short-term policy rates influence borrowing costs and market interest rates.
Inflation
Higher inflation can reduce the appeal of fixed payments.
Economic Growth
Strong growth may lead investors to expect higher rates, while weaker growth can support demand for safer fixed-income assets.
Credit Conditions
Corporate bond prices can decline when investors become more concerned about default risk.
Investor Risk Appetite
During periods of uncertainty, investors may shift toward high-quality government bonds.
The bond market therefore reflects both interest-rate expectations and perceptions of credit risk.
Bond Spreads
A credit spread measures the difference between the yield on a bond and the yield on a benchmark security with similar maturity.
Suppose a corporate bond yields:
6%
while a comparable government bond yields:
4%
The spread is:
2 percentage points
or approximately:
200 basis points
Wider spreads generally indicate that investors require more compensation for credit risk.
Basis Points
Bond markets frequently express yield changes in basis points.
One basis point equals:
0.01 percentage point
So:
100 basis points = 1 percentage point
If a yield rises from 4.00% to 4.50%, it increased by:
50 basis points
This terminology makes small rate changes easier to communicate.
Bond Market and the Economy
Bond markets can influence the broader economy because borrowing costs affect:
- mortgages;
- corporate loans;
- government financing;
- investment decisions.
Higher yields can increase financing costs for businesses and consumers.
Lower yields can reduce borrowing costs, although the broader economic effect also depends on credit availability and demand.
Bonds and Corporate Financing
Companies choose between different financing sources.
These can include:
- retained earnings;
- bank loans;
- bonds;
- equity.
Bond issuance can allow a company to borrow large amounts from capital markets rather than relying entirely on banks.
However, debt creates fixed obligations.
Management needs to consider whether future cash flow can support:
- interest payments;
- principal repayment.
This is why bond issuance is closely connected to capital structure and financial risk.
Bonds and Portfolio Diversification
Investors often combine bonds with stocks because the two asset classes can respond differently to economic conditions.
Bonds may provide:
- income;
- lower volatility;
- diversification.
However, the relationship is not constant.
Stocks and bonds can sometimes fall at the same time, especially during periods of rapidly rising inflation or interest rates.
Diversification reduces dependence on one source of return but does not eliminate market risk.
Bonds for Long-Term Investors
For someone focused on investing in the stock market, bonds can still play an important portfolio role by providing a different risk and income profile.
The appropriate allocation depends on:
- financial goals;
- investment horizon;
- liquidity needs;
- risk tolerance.
An investor with a long time horizon may accept greater equity exposure, while someone who needs more predictable income may allocate more to fixed income.
There is no universal stock-to-bond ratio appropriate for every investor.
Individual Bonds vs Bond Funds
Individual bonds and bond funds provide different experiences.
Individual Bonds
Potential advantages:
- known maturity date;
- defined face value;
- predictable cash-flow schedule.
Potential limitations:
- diversification can require significant capital;
- individual securities can be difficult to research.
Bond Funds
Potential advantages:
- easier diversification;
- professional management;
- convenient trading.
Potential limitations:
- no single maturity date;
- fund prices can remain below the investor’s purchase price.
The appropriate choice depends on the investor’s goals and resources.
Example: Bond Price and Interest Rates
Suppose an investor owns a ten-year bond paying:
4%
Soon after purchase, similar new bonds begin paying:
6%
The original bond becomes less attractive.
Its price may fall below par until its yield becomes more competitive.
If the investor holds the bond until maturity and the issuer pays as promised, short-term market-price changes may be less important.
If the investor needs to sell early, those price changes become very relevant.
Example: Credit Risk
Company A and Company B each issue five-year bonds.
Company A has:
- strong cash flow;
- low debt.
Company B has:
- weak earnings;
- high leverage.
Investors may require:
4.5% from Company A
and:
8% from Company B.
The higher yield on Company B compensates investors for greater perceived credit risk.
The higher yield does not guarantee a better investment result if the company later defaults.
Example: Inflation Risk
Suppose an investor buys a long-term bond yielding:
3%
Inflation unexpectedly rises to:
6%
The purchasing power of the bond’s fixed payments declines.
Market interest rates may also rise, causing the bond’s price to fall.
The investor therefore faces both:
- real purchasing-power loss;
- market-price decline.
Common Bond Investing Mistakes
Mistake 1: Assuming Bonds Cannot Lose Money
Investors treat fixed income as risk-free.
Why it fails: Bond prices can decline and issuers can default.
Mistake 2: Chasing the Highest Yield
The highest-yielding bond appears most attractive.
Why it fails: Higher yield often reflects greater credit or liquidity risk.
Mistake 3: Ignoring Duration
Investors focus only on coupon income.
Why it fails: Long-duration bonds can fall significantly when rates rise.
Mistake 4: Confusing Coupon With Return
A bond pays 5%, so the investor assumes the return is always 5%.
Why it fails: Market price, maturity, and reinvestment affect total return.
Mistake 5: Ignoring Inflation
Fixed payments appear stable.
Why it fails: Purchasing power can decline.
Mistake 6: Assuming All Government Bonds Are Equal
Government debt is treated as one risk category.
Why it fails: Countries have very different currencies, fiscal positions, and credit conditions.
Mistake 7: Ignoring Call Features
A high coupon looks attractive.
Why it fails: The issuer may redeem the bond early when rates fall.
Mistake 8: Ignoring Liquidity
The quoted price appears reliable.
Why it fails: Thinly traded bonds may be difficult to sell near the quoted value.
How to Evaluate a Bond
Before buying a bond, investors can review several factors.
Issuer
Who is borrowing the money?
Credit Quality
How likely is the issuer to meet its obligations?
Yield
What return does the bond offer relative to its price?
Maturity
When is principal scheduled to be repaid?
Duration
How sensitive is the bond to interest-rate changes?
Call Features
Can the issuer repay early?
Liquidity
How easily can the bond be traded?
Currency
Is the bond denominated in the investor’s home currency?
Evaluating these factors together provides a more complete picture than simply comparing coupon rates.
A Practical Bond Market Checklist
Before investing in bonds, ask:
- Who issued the bond?
- What is the issuer’s credit quality?
- What is the maturity?
- What yield am I actually receiving?
- How sensitive is the bond to interest rates?
- Is the bond callable?
- How liquid is the security?
- What happens if inflation rises?
- Is currency risk involved?
- How does the bond fit within the overall portfolio?
These questions help investors focus on the actual sources of return and risk.
Key Takeaways
The bond market allows governments, companies, and other organizations to borrow money from investors by issuing debt securities.
Bonds typically involve:
- principal;
- coupon payments;
- maturity;
- market yield.
Important bond categories include:
- government bonds;
- corporate bonds;
- municipal bonds;
- investment-grade bonds;
- high-yield bonds.
Bond prices can change because of:
- interest rates;
- inflation;
- credit quality;
- liquidity;
- investor expectations.
Major risks include:
- interest-rate risk;
- credit risk;
- inflation risk;
- liquidity risk;
- reinvestment risk;
- call risk.
Bonds can provide income and diversification, but they should not be treated as automatically safe. Understanding how bond prices, yields, maturities, and credit quality interact is essential for evaluating fixed-income investments.
FAQ
What is the bond market in simple terms?
The bond market is the financial market where governments, companies, and other organizations issue and trade debt securities. Investors lend money to issuers in exchange for interest and expected repayment of principal.
How does a bond work?
An investor buys a bond and provides capital to the issuer. In return, the issuer generally agrees to pay interest and repay the bond’s face value at maturity.
Why do bond prices fall when interest rates rise?
Existing bonds become less attractive when newly issued bonds offer higher yields. Their market prices may fall so their effective yields become more competitive.
What is bond yield?
Bond yield measures the return generated by a bond relative to its price. Common measures include current yield and yield to maturity.
What is the difference between a bond and a stock?
A bond represents debt, while a stock represents ownership. Bondholders are creditors, whereas shareholders own part of the company.
What is a corporate bond?
A corporate bond is debt issued by a company to raise capital. Investors lend money to the company and receive interest according to the bond’s terms.
Can bonds lose value?
Yes. Bond prices can fall because of rising interest rates, deteriorating credit quality, inflation, or changing market conditions.
What is duration in bonds?
Duration estimates how sensitive a bond or bond portfolio is to changes in interest rates. Higher duration generally means greater price sensitivity.
What is a high-yield bond?
A high-yield bond is debt issued by a lower-rated borrower. It typically offers a higher yield to compensate investors for greater credit risk.
Are bonds safer than stocks?
Bonds often have lower volatility and a higher claim priority than common stocks, but their risk depends on the issuer, maturity, credit quality, interest rates, and other factors. Bonds are not risk-free.